French Decree 2026-420 of 29 May 2026 clarifies ownership transfers and pledges over crypto-assets. Published on 31 May, it entered into force on 1 June 2026; several MiCA-related terminology changes took effect on 1 July. It implements an existing legal framework, including provisions introduced by the Act of 30 April 2025. It does not create a right to borrow or a general tax exemption.
For a business, the practical opportunity is to consider financing secured by assets it already owns, with identifiable contractual requirements, ownership evidence and enforcement rules. Whether financing is available still depends on the lender, eligible assets and repayment capacity. Read the decree and its commencement provisions on Légifrance, in French.
When does ownership transfer?
Submitting an order, seeing a transaction and reaching final settlement are not necessarily simultaneous. Article R. 226-1 distinguishes two situations:
- Registration on a distributed ledger: ownership transfers when the entry in the purchaser’s favour becomes irreversible under that ledger’s consensus mechanism. Broadcasting a transaction alone is insufficient.
- Custody with a service provider: the relevant event is the entry of the purchaser’s position in the provider’s position register. This must occur as soon as possible after settlement.
Keep execution confirmations and custody statements alongside transaction references. A blockchain explorer will not necessarily show a platform’s internal transactions. The ownership rules and evidence of the signatory’s authority need to be considered together.
What the pledge documentation should cover
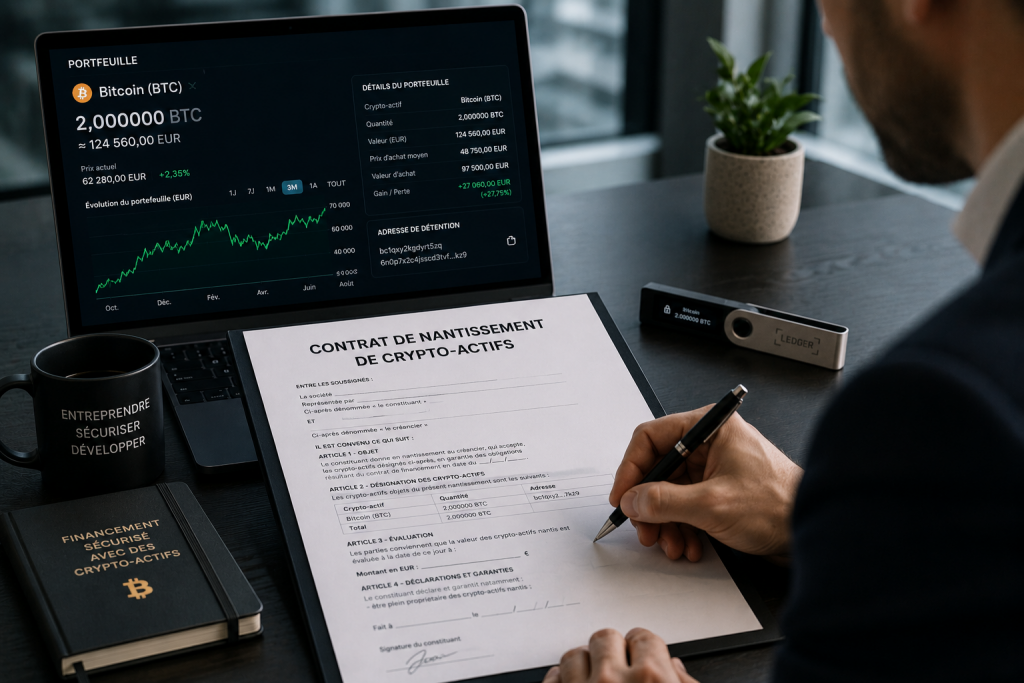
A pledge allocates assets as security for a debt. The declaration identifies the parties, signing date, secured claim, assets and quantities, together with the relevant ledger addresses or custody account. Adding collateral may require a supplementary declaration.
Where the parties use a smart contract, the decree requires safeguards for information integrity, traceability and retention. Deploying code does not replace an accessible contractual record. Where a custodian holds the assets, it must receive the agreed conditions and respect the secured creditor’s rights.
The arrangement should explain who may move the assets, receive their proceeds and issue instructions. Review withdrawal restrictions, charges, collateral substitution and the applicable law. A product marketed as a “crypto loan” may use a different legal structure: read the contract before assuming that the French pledge regime applies.
The central risk: topping up collateral at an inconvenient time
Consider an illustrative company borrowing €200,000 against a portfolio valued at €800,000. Its loan-to-collateral ratio would initially be 25%. If the portfolio fell to €400,000, the ratio would reach 50% even though the debt had not changed. This calculation is neither a lending offer nor an indication of a bank’s accepted thresholds.
The contract determines any margin calls, deadlines and default consequences. The business needs to meet those obligations without jeopardising payroll, tax or supplier payments. Model market declines, reduced liquidity and provider outages, including interest and fees.
Compare the arrangement with a partial sale, conventional borrowing or a smaller funding requirement. Keeping market exposure is not always the best fit. Our guide to crypto-backed Lombard loans discusses questions to consider before committing personal or company assets.
Tax and accounting follow the actual contract
Creating a straightforward pledge without transferring ownership is not, by itself, a sale. However, distinguish a pledge from an asset loan, a title-transfer security arrangement or asset reuse. Enforcement may lead to assets leaving the holder’s estate and have tax consequences, depending on the mechanism and the holder’s tax regime. The decree does not grant blanket tax neutrality to these arrangements.
Under a conventional pledge, the owner continues to track the assets on its balance sheet and documents their use as collateral. Reconcile the financing amount, pledged quantities, valuations and restrictions on availability. Financial statement disclosures depend on the applicable accounting framework.
ANC Regulation 2026-01 applies mandatorily to financial years starting on or after 1 January 2027. Early adoption is permitted for the financial year in progress when it was published in the French Official Journal on 3 September 2026. A 2026 closing therefore requires an explicit assessment of the framework adopted. Read our explanation of the ANC regulation.
Documents to assemble before signing
- The articles of association, the signatory’s powers and approval by the competent corporate body, supported by the company’s interests.
- An inventory of the assets, their origin, relevant accounts and addresses, and ownership evidence.
- The financing agreement and pledge declaration, reviewed for their legal and tax implications.
- The custodian’s terms, where relevant, its authorisation for the services provided and the procedure for recording the security arrangement.
- A cash-flow forecast covering interest, possible margin calls and other business commitments.
- A monitoring procedure identifying responsibilities, review frequency, alert thresholds and records supplied to the accountant.
Frequently asked questions
Must every bank accept crypto collateral?
No. The legal framework does not require a lender to finance a transaction or accept an asset. Credit criteria, eligible assets and custody requirements remain subject to agreement.
Does shareholder approval automatically protect a director?
No. It records the decision-making process but does not replace proper authority, the company’s interests or a risk assessment. The circumstances must be considered as a whole.
What should we prepare for an initial discussion?
Your funding need, repayment dates, asset inventory and the lender’s proposed agreement provide a useful starting point. Discuss your project with the firm.