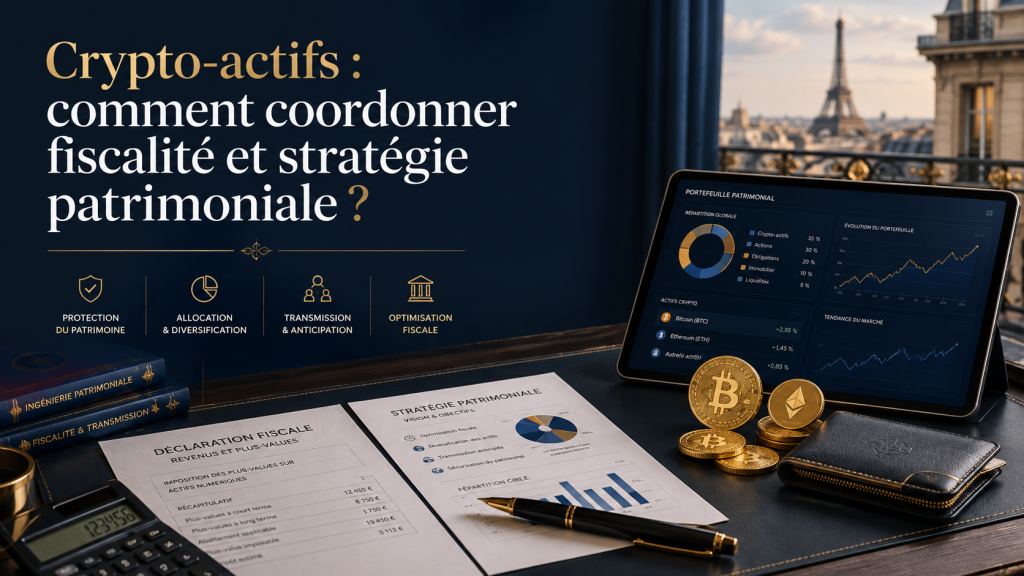
Crypto-assets can become a significant part of an individual's or company's wealth. Their management is often divided into separate questions: reporting and tax on one side; investment, risk and long-term goals on the other. That separation can leave important gaps.
A correctly reported portfolio may still be disproportionately risky. Conversely, a seemingly coherent wealth decision can have accounting, tax or documentation consequences that were not anticipated. Coordination helps advisers work from the same facts.
Why taxation and wealth planning interact
Tax analysis asks about the consequences of transactions already completed or being considered. Wealth planning asks what role crypto-assets should play in the person's overall finances.
After a sharp price rise, the crypto share of a portfolio can increase without a deliberate allocation decision. Selling, gifting, transferring or using those assets to fund a project may then affect both risk and tax.
A decision should therefore be assessed after considering liquidity, loss-bearing capacity, obligations and personal or business objectives.
The accountant establishes the transaction picture
Crypto-assets move across exchanges, wallets, protocols and bank accounts. A displayed portfolio value does not explain ownership, acquisition history or the nature of the transactions.
- List the platforms, wallets and accounts used.
- Trace purchases, sales, exchanges, transfers and income.
- Identify the person or entity that actually owns the assets.
- Separate personal and company transactions.
- Retain original exports and supporting evidence.
- Assess the accounting or tax consequences of proposed transactions.
HODL Consulting works on traceability, accounting and tax questions within the agreed assignment. The resulting information can support the client's other advisers, with any reconstruction limits made explicit.
When the question becomes one of wealth planning
Two people holding the same amount of bitcoin may have very different capacities to bear a loss. Income, debts, other assets, planned expenditure and time horizons matter.
A wealth review considers concentration in assets and providers, short- and medium-term liquidity, personal and business exposure, and projects such as property purchases, retirement or succession. There is no universal ideal crypto percentage.
The original article presents WhiteBlock's role as integrating crypto-assets into a broader wealth strategy, alongside the professionals responsible for accounting, tax and legal work. Each provider must confirm its actual permissions and engagement scope.
Four common blind spots
A portfolio that has outgrown the original allocation
A market rise can turn a modest position into a major share of financial wealth. Even without a new purchase, the risk profile has changed.
A euro-denominated project funded by volatile assets
A property purchase or capital contribution needs an amount available on a specific date. Leaving the required funds exposed until the last moment can jeopardise the project; an urgent sale may also create unprepared documentation and tax work.
Personal conviction applied to company cash
A director's willingness to accept volatility does not establish the company's capacity to do so. The business still needs to fund wages, charges, investment and contingencies.
Assets that heirs cannot access
Knowing that a wallet exists does not establish a workable succession plan. Inventory, legal rights, valuation and secure access arrangements need to be coordinated.
An illustrative case
Thomas is a fictional director of a profitable company. He owns crypto personally and is considering a company investment. Within two years, he also wants to buy property and begin planning the transfer of his wealth.
HODL Consulting can distinguish personal and business flows, review available history and assess the accounting or tax consequences of the scenarios. A wealth adviser can then examine the total exposure, property-project liquidity and concentration of risk.
A notary, lawyer or authorised crypto provider may be needed for implementation. The purpose is to ensure that advisers use the same underlying facts and understand the boundaries of their work.
Define responsibilities
| Question | Accounting and tax work | Wealth-planning work |
|---|---|---|
| History and evidence | Review ownership, transactions and records | Use documented information in the overall assessment |
| Tax and accounting consequences | Assess within the engagement | Incorporate the consequences into scenarios |
| Exposure, liquidity and goals | Explain business and tax constraints | Assess the broader allocation and objectives |
| Implementation | Follow accounting and reporting requirements | Coordinate the strategy with relevant authorised professionals |
This is an indicative division. It does not expand any professional's legal permissions or replace an engagement letter.
A sequence for major decisions
- Build the inventory of assets, accounts, owners and records.
- Clarify past transactions and the consequences of proposed changes.
- Review overall assets, liabilities, income and goals.
- Compare scenarios for holding, reducing exposure, raising cash or transferring wealth.
- Coordinate implementation with the required advisers.
- Review the position when values, goals or rules change.
Frequently asked questions
Which adviser should come first?
If ownership or history is unclear, accounting reconstruction is often the starting point. If the facts are documented and the question concerns long-term objectives, wealth analysis can begin immediately. Complex cases may require both in parallel.
Does a compliant return mean the portfolio is well structured?
No. Reporting compliance and suitability for the person's goals are different assessments.
Why act before a major disposal?
Preparation gives time to gather evidence, compare scenarios and coordinate liquidity, tax and implementation.
The original contributor note identifies WhiteBlock Invest with ORIAS number 25000825. That historical identification is not a substitute for checking its current register entry and permissions before an engagement. This article provides general education, not a personalised investment or tax recommendation.